Watts, Wires and Wallet: The Real Reason Your UK Cloud Bill Keeps Creeping Up
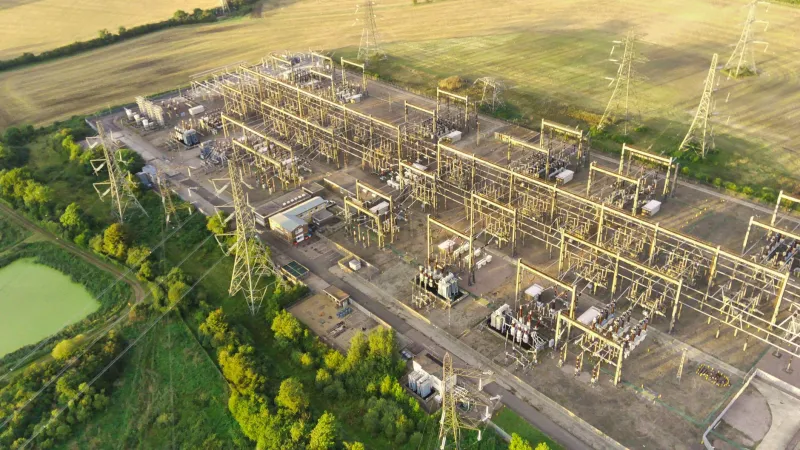
You know the feeling. The invoice lands, the total is up another seven per cent, and the line items still read like they were written by someone who didn't want to be in the room. Compute, storage, 'network services', a surcharge with a name nobody can parse. Nowhere does it say the actual reason: the substation down the road is full.
That's the story behind UK cloud pricing in 2026, and it's worth understanding properly, because it changes how you should be buying.
A data centre is no longer a building. It's a power contract.
For the best part of two decades, the binding constraint on UK data centre capacity was land and planning permission. Find a shed near the M4, fill it with racks, done. That era is over.
The thing you now have to queue for is megawatts. The western corridor around Slough, Hayes and Park Royal is one of the densest concentrations of digital infrastructure in Europe, and the local grid has been asked to carry far more than it was designed for. Developers have been quoted connection dates stretching into the 2030s for new high-voltage supply. Some have simply gone elsewhere - to South Wales, the North East, or Scotland, where the wind farms are and the wires are less crowded.
Layer on top of that the ongoing reform of how electricity is charged to large users - transmission charges, the shift towards more localised price signals, the long-running shake-up of national pricing - and you get a market where the cost of a kilowatt-hour varies far more by postcode than it used to.
You don't buy electricity. Your cloud provider does. But you absolutely pay for it.
Four ways the grid reaches your invoice
Energy pass-through. Most hyperscalers don't hide power costs entirely. They fold them into list prices, and some contracts include clauses allowing adjustments when energy markets move. When wholesale prices spike - and they still do, in sudden, weather-driven lurches - someone eventually absorbs that. Usually you, quietly, via the next price revision.
The regional premium. Capacity scarcity is priced. A region sitting inside a congested part of the grid, with limited room to grow, will generally cost more than a region built next to generation. It isn't a conspiracy, it's supply and demand with a transformer bolted on. If all your workloads live in the London region out of habit, you're paying an address premium.
Density and cooling. The AI-driven rush towards high-density racks has made cooling the single hardest engineering problem in the sector. Getting 40kW into a rack in a 2010s building is a job. That capital cost gets recovered from the customers who need the newest, densest kit - which, increasingly, means anyone running serious GPU workloads.
Interconnect and egress. Power isn't the only constrained thing. Cross-connects in the busiest carrier hotels are priced like London parking. Moving data between regions can cost more than computing it.
Why London still isn't automatically the wrong answer
It would be easy to write 'move everything to Newcastle'. That would be lazy advice. Location is still dominated by latency, and for trading systems, real-time payments, contact centre platforms and anything with a human waiting, single-digit milliseconds matter. The London region exists because the customers are there.
The better question is: which of your workloads genuinely needs to sit in the most expensive, most congested part of the country? A nightly ETL job that churns through yesterday's transactions does not care about four milliseconds. Nor does a backup target, a staging environment, or a media transcoding farm. Yet these things end up in the same region as the customer-facing app because that's where they were born in 2019 and nobody has moved them since.
What a finance lead should ask a tech lead
- Which regions are we actually using, and what's the split of spend between them?
- Of that, how much is non-production, batch or archival?
- If we moved the batch stuff one region north, what would break?
- Do we have any contract clauses that let the provider increase prices mid-term, and how much notice do we get?
- What's our committed-spend position versus our actual run rate?
Blunt questions, but they tend to surface a surprising amount of accidental cost.
What a tech lead should ask the provider
- How are energy costs reflected in your pricing, and what notice do we get on adjustments?
- What's the realistic capacity runway in this region for the instance families we rely on?
- Are there discounts for workloads that can be flexible about when they run?
- What are the egress charges between the regions we'd consider?
- Is there a sovereign or in-country option, and how does its price compare?
A 90-day plan that won't require a project board
Weeks one to three: tag everything properly. You cannot optimise a bill you can't attribute. A top-three cost centre breakdown by region and environment usually pays for the exercise on its own.
Weeks four to six: kill the zombies. Unattached storage volumes, idle dev boxes left running over bank holidays, over-provisioned databases that were sized for a launch that never came. This is unglamorous and it is where most of the money is.
Weeks seven to nine: pilot a regional move for one non-critical batch workload. Measure the real saving including egress and the engineering time. You'll learn more from one migration than from three months of business cases.
Weeks ten to twelve: take your commitments to market. Reserved capacity, savings plans and spot for anything tolerant of interruption. If you're renewing, negotiate the price-change clause, not just the discount.
The uncomfortable conclusion
Cloud pricing in the UK is drifting away from the clean, abstract, per-hour model the marketing still promises, and towards something that looks a lot more like utilities and commercial property: constrained, localised, and negotiated. That's not bad news. It just means the procurement conversation has changed. Power is the new real estate, and the teams who treat it that way - who know which workloads can move and which cannot - will keep finding headroom while everyone else quietly renews at the higher number.
Get the tagging right this quarter. It's the cheapest thing you'll do all year.